NBFC Lending in India Reaches ₹61.7 Lakh Crore as Gold and Consumer Loans Surge
India's NBFC credit expanded 15.4% in September, led by retail lending, while industrial credit growth moderated.
Why India’s non-banking lenders are expanding retail credit rapidly, while industrial lending loses momentum and regulators face new questions about household borrowing.
India’s non-banking financial companies (NBFCs) are expanding their lending business, with retail borrowers accounting for a growing share of credit demand. The latest Reserve Bank of India data show that outstanding NBFC credit reached ₹61.7 lakh crore in September 2026, marking annual growth of 15.4%.
The expansion was particularly strong in retail lending. Credit to individuals increased by 21.9% year-on-year, compared with 16.8% in September 2025. Gold-backed loans, housing finance and vehicle loans contributed to the increase.
However, the picture was different across other sectors. Industrial credit growth slowed to 7.4%, while lending to services businesses moderated from its previous year’s pace.
The figures reveal a changing pattern in India’s credit market. NBFCs are expanding their role in household finance, but industrial borrowing is not keeping pace with retail demand.
NBFC Credit Reaches ₹61.7 Lakh Crore
The RBI’s September 2026 sectoral credit data, released on November 6, show that outstanding lending by NBFCs increased from ₹53.46 lakh crore in September 2025 to ₹61.7 lakh crore in September 2026.
The annual growth rate also improved from 13.3% in September 2025 to 15.4% in September 2026.
This expansion reflects the growing importance of non-bank lenders in India’s financial system.
NBFCs provide credit to individuals and businesses that may have different borrowing requirements from customers served by traditional banks. Their products include vehicle finance, consumer loans, gold loans, housing finance, business loans and infrastructure funding.
Their presence is particularly important in segments where specialised lending models, local distribution networks and faster credit assessment can improve access to finance.
However, the increase in outstanding credit should not automatically be interpreted as an improvement in every borrower’s financial position. The quality of lending, repayment performance and cost of borrowing also matter.
Retail Loans Are Driving the Expansion
Retail lending has emerged as the strongest growth area in the latest data.
NBFC retail credit grew 21.9% year-on-year in September 2026, compared with 16.8% in the same month a year earlier.
Outstanding retail loans reached ₹26.84 lakh crore, accounting for approximately 44% of total NBFC credit.
This growth indicates that individual borrowers are becoming increasingly important to the business models of non-bank lenders.
Housing finance supports property purchases and residential construction. Vehicle loans help households and businesses finance cars and commercial vehicles. Gold loans provide access to money against pledged jewellery.
Consumer finance also allows households to spread the cost of appliances, electronics and other purchases over time.
For lenders, retail portfolios can provide opportunities to diversify revenue across large numbers of borrowers. However, rapid expansion requires strong credit assessment and monitoring.
Gold Loans Become a Major Growth Driver
Gold-backed lending is receiving particular attention because of its rapid expansion.
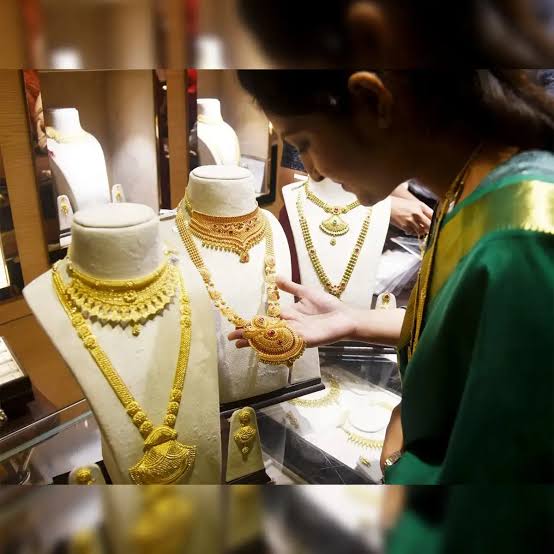
Moneycontrol reported on November 6 that gold loans were among the fastest-growing NBFC lending segments, with growth of approximately 66% year-on-year.
Gold loans allow borrowers to obtain credit by pledging jewellery or other eligible gold assets.
The structure can be attractive to customers who need funds quickly or have limited access to conventional unsecured borrowing.
Small businesses, traders and households may use these loans to manage temporary cash-flow requirements, medical expenses or working-capital needs.
For lenders, pledged gold provides collateral that can reduce certain credit risks compared with unsecured lending.
However, this does not make gold loans risk-free. A fall in gold prices can reduce collateral coverage. Borrowers may also face difficulties repaying loans when income is irregular.
Lenders must therefore monitor loan-to-value ratios, repayment schedules and the quality of collateral management.
Housing and Vehicle Finance Continue to Expand
The RBI also reported accelerated growth in housing and vehicle loans during September.
Housing finance remains an important part of the NBFC market because specialised housing finance companies serve customers across different income groups and geographical regions.
These lenders can provide financing to households purchasing homes, constructing properties or meeting other eligible housing requirements.
Vehicle loans also recorded stronger growth. Demand can come from private vehicle purchases, commercial transport operators and businesses that require vehicles for distribution and logistics.
The two categories have different economic implications.
Housing finance supports the residential property market and related industries such as cement, steel, construction and building materials.
Vehicle finance can support automobile sales, transportation activity and commercial mobility.
The strength of these segments suggests that retail credit demand remains an important part of India’s domestic financial activity.
Industrial Lending Is Losing Momentum
While retail lending accelerated, industrial credit growth moved in the opposite direction.
The RBI reported that NBFC credit to industry grew by 7.4% year-on-year in September 2026, compared with 10.2% in September 2025.
The moderation was particularly relevant because industrial lending supports businesses investing in production capacity, machinery and long-term infrastructure.
Within the industrial segment, infrastructure-related credit growth remained subdued.
This creates an important contrast in the credit market.
Household borrowing is expanding faster, while lending to industrial businesses is growing more slowly.
There are several possible reasons for this difference. Industrial projects often require longer approval periods and larger financing commitments. Businesses may also delay investment when they face uncertainty over demand, project costs or future returns.
NBFCs may be more cautious when financing projects that involve long repayment periods and complex execution risks.
The latest figures do not establish that industrial investment is declining. They show that the growth of NBFC lending to industry has moderated.
Services Lending Is Also Moderating
NBFC credit to the services sector grew 17.3% year-on-year in September, compared with 23% a year earlier.
The moderation suggests that the pace of expansion has slowed, although several service-related categories continued to show strong activity.
Commercial real estate recorded buoyant credit growth. Lending to trade and transport operators also increased.
These segments are important because they connect financial activity with the wider economy.
Commercial real estate borrowing can support office developments, business premises and other income-generating properties.
Trade finance helps businesses purchase and distribute goods, while transport operators require funding for vehicles, equipment and working capital.
The different performance across services categories highlights why aggregate lending figures should be examined alongside sector-level data.
Why Borrowers Are Turning to NBFCs
NBFCs have developed specialised lending models that allow them to serve different categories of borrowers.
Their distribution networks can reach customers in smaller cities and towns. Some lenders use alternative information and customised assessment methods to evaluate borrowers who may not fit conventional bank lending models.
They also provide products designed around specific assets or financial needs.
For example, a gold loan is secured against pledged jewellery. A vehicle loan is linked to the financed vehicle. Housing finance is backed by property-related security.
These structures help lenders develop products for different customer groups.
However, the cost of borrowing can vary significantly between institutions and products. Borrowers need to examine interest rates, processing fees, repayment conditions and penalties before accepting credit.
What the Growth Means for Financial Stability
Rapid retail lending creates opportunities, but it also requires careful supervision.
When credit expands quickly, lenders must ensure that borrowers can manage repayments without taking on excessive financial obligations.
Multiple loans across different institutions can make it difficult to assess a customer’s total debt exposure.
Gold loans also require effective collateral valuation. Housing and vehicle loans need reliable asset assessments and repayment monitoring.
For NBFCs, the quality of underwriting becomes especially important during periods of rapid expansion.
Regulators monitor capital adequacy, liquidity, asset quality and lending practices to reduce the risk of excessive risk-taking.
The RBI’s oversight is important because NBFCs are closely connected to banks, mutual funds and other parts of the financial system through borrowing and investment relationships.
Problems in a large lending institution can therefore affect more than its direct customers.
The Competitive Position of Banks and NBFCs
NBFCs compete with banks, but their roles are not identical.
Banks have access to a broader deposit base and provide a wide range of financial services. NBFCs often focus on specific lending categories and customer groups.
Some NBFCs borrow from banks and other financial institutions to finance their loan portfolios. Others raise funds through bonds, commercial paper and equity.
This makes funding costs a major factor in their profitability.
When borrowing costs rise, lenders may find it harder to maintain attractive interest margins. They may also increase loan rates or become more selective about new borrowers.
The ability to maintain asset quality while controlling funding expenses will influence the next phase of NBFC growth.
What Investors Should Watch
The September figures provide a useful view of the changing credit market, but investors should examine more than loan growth.
Important indicators include:
- Asset quality: Whether overdue loans and non-performing assets are increasing.
- Funding costs: Whether NBFCs can raise money at competitive rates.
- Retail concentration: Whether rapid household lending creates excessive exposure to a single segment.
- Gold loan quality: Whether collateral coverage remains sufficient as lending expands.
- Industrial credit: Whether business financing begins to recover.
- Capital adequacy: Whether lenders maintain sufficient capital to support expansion.
Companies with strong risk management and diversified funding may be better positioned to manage changes in the credit cycle.
India’s NBFC sector is becoming increasingly important to household and business finance. The latest data show that retail borrowing is driving much of its expansion, with gold, housing and vehicle loans contributing to growth. Yet slower industrial lending highlights an uneven credit recovery. The next stage will depend on whether lenders can maintain responsible retail expansion while supporting productive business investment. Strong loan growth can improve financial access, but sustainable credit depends on repayment capacity, asset quality and prudent lending standards.
Samir Kapoor
Samir Kapoor covers the global economy, cross-border capital, growth signals and the institutions shaping economic change.


