India Opens New Overseas Fundraising Routes for Companies Through GIFT City
India's revised overseas listing rules expand fundraising options for companies and strengthen GIFT City's role in international capital markets.
How revised listing rules could help Indian businesses access international capital through convertible debentures, preference shares and overseas stock exchanges.
Indian companies are getting more flexibility to raise capital from international markets. The government has expanded the overseas listing framework to cover additional financial instruments and a wider group of eligible businesses. The changes could make international fundraising more accessible, particularly for companies operating through Gujarat’s GIFT City.
The Ministry of Corporate Affairs notified the Companies (Listing of Equity Instruments in Permissible Jurisdictions) Amendment Rules, 2026, on November 3. The revised framework allows Indian companies to list convertible debentures and preference shares overseas, alongside equity shares. It also creates a route for eligible unlisted public companies operating in International Financial Services Centres (IFSCs) to list their securities abroad.
The changes reflect India’s effort to connect domestic businesses with international capital markets. They also strengthen the role of GIFT City as a financial centre for cross-border fundraising.
What Has Changed in the Overseas Listing Rules?
The earlier framework primarily focused on the overseas listing of equity shares. The amended rules broaden the definition of eligible equity instruments.
Companies can now use three categories of instruments under the framework:
- Equity shares: Ownership instruments that represent a stake in a company.
- Convertible debentures: Debt instruments that can be converted into equity under specified conditions.
- Preference shares: Instruments that generally provide preferential rights over ordinary equity shares for dividends or repayment of capital.
This gives companies more flexibility when structuring international fundraising.
Not every business needs to issue ordinary shares to raise money. Some may prefer debt-linked instruments or preference capital, depending on their financial position, investor requirements and long-term funding plans.
The revised framework provides a wider range of options, subject to the rules and regulations of the relevant overseas jurisdiction.
Why GIFT City Has a Bigger Role
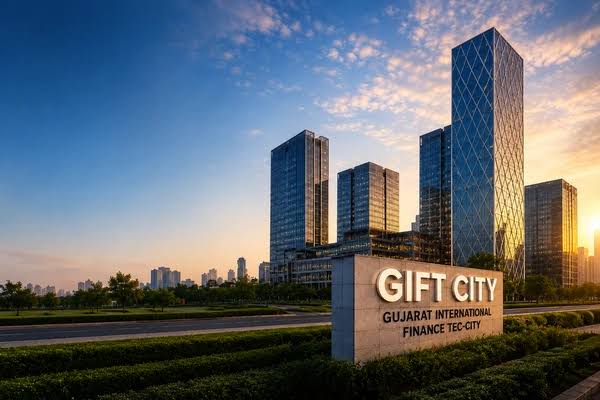
GIFT City, located in Gujarat, is India’s International Financial Services Centre. It is designed to provide an internationally oriented financial ecosystem for activities such as banking, insurance, fund management, capital markets and financial services.
The new rules allow eligible unlisted public companies operating within an IFSC jurisdiction to use the overseas listing framework, provided they comply with the International Financial Services Centres Authority’s regulations.
This is an important development for GIFT City because it connects the IFSC regulatory environment with the broader overseas fundraising framework.
Companies operating in the centre may gain additional flexibility in accessing international investors without first following the same listing route as companies operating outside the IFSC.
However, eligibility is not automatic. Businesses must meet the applicable requirements and comply with IFSCA regulations and the rules of the relevant securities market.
Companies With Negative Net Worth Get a Conditional Route
One of the more significant changes concerns companies with negative net worth.
Under the amended framework, a company with negative net worth can become eligible to issue equity instruments for overseas listing if it undertakes to allocate at least 75% of the net offer to qualified institutional buyers.
Qualified institutional buyers generally include large professional investment institutions that meet the applicable regulatory definition.
The requirement creates a safeguard by directing most of the offer towards institutional investors rather than relying primarily on smaller individual investors.
This provision could provide a fundraising route for companies that have experienced financial difficulties but still have a viable business model or restructuring plan.
However, eligibility to list does not mean that investors will automatically provide capital. Companies must still demonstrate credible financial prospects, governance standards and a convincing business case.
A Shorter Waiting Period After Loan Repayment
The amendment also changes the waiting period for companies that have repaid overdue loans to banks and financial institutions.
The previous framework referred to a two-year waiting period. The amended rules replace this with a period of more than six months.
This change could make overseas fundraising more accessible to businesses that have addressed their repayment defaults and are seeking fresh capital.
For companies undergoing financial restructuring, the shorter period may reduce delays in returning to capital markets.
The amendment also clarifies the treatment of defaults that have not been made good. Companies must still satisfy the relevant eligibility conditions, and a history of financial difficulty does not automatically disappear because a payment has been made.
The revised rules therefore offer greater flexibility while retaining conditions intended to protect market integrity.
Why Convertible Debentures and Preference Shares Matter
The inclusion of additional instruments is important because companies have different capital requirements.
Equity issuance can dilute existing shareholders. A business that issues new shares may reduce the ownership percentage of its current investors.
Convertible debentures offer another structure. They begin as debt and may convert into equity according to agreed terms. This can help companies attract investors who want a defined instrument with potential participation in future equity value.
Preference shares can provide investors with preferential dividend or capital repayment rights, depending on their terms.
For businesses, these instruments can help structure fundraising around their cash flows, ownership priorities and investment requirements.
For investors, they offer different combinations of income, conversion rights, ownership exposure and risk.
The actual terms matter. Companies and investors will need to examine conversion prices, dividend provisions, repayment obligations, voting rights and other contractual conditions before committing capital.
What This Means for International Investors
The expanded framework could create more opportunities for international institutional investors to participate in Indian corporate fundraising.
Foreign investors often assess companies through factors such as financial reporting, corporate governance, regulatory compliance, liquidity and the legal enforceability of investor rights.
Overseas listing can place Indian businesses within a wider investment ecosystem. It may also help them connect with investors who specialise in particular sectors or funding instruments.
However, international fundraising carries additional responsibilities. Companies must comply with the disclosure standards, securities regulations and reporting requirements applicable in the chosen jurisdiction.
Currency movements can also affect the cost of raising and repaying foreign capital. Businesses that raise funds in overseas currencies need to consider exchange-rate exposure and the structure of their future financial obligations.
GIFT City’s Competition With International Financial Centres
GIFT City is seeking to attract financial activity that has traditionally been conducted through established international centres.
Its growth depends on more than tax or regulatory incentives. It needs strong financial institutions, market infrastructure, professional services, global investor participation and confidence in its regulatory framework.
The expanded listing rules could improve its appeal by giving eligible companies more ways to raise capital internationally.
They may also support the development of related services, including legal advisory, auditing, investment banking, compliance and fund management.
But competition remains strong. Businesses compare financial centres based on market depth, investor access, regulatory clarity, costs and the ease of executing transactions.
The effectiveness of the revised rules will therefore depend on whether companies actually use them and whether international investors respond.
What Companies Must Consider Before Listing Abroad
The expanded framework creates new options, but companies should evaluate the commercial and regulatory implications before choosing an overseas listing route.
Important considerations include:
- Investor suitability: Whether the selected market has investors interested in the company’s sector and financial instruments.
- Regulatory compliance: Whether the company meets the requirements of the relevant overseas jurisdiction and IFSCA, where applicable.
- Financial reporting: Whether its accounts, disclosures and governance systems meet the required standards.
- Capital structure: Whether equity, convertible debentures or preference shares best fit its funding needs.
- Currency exposure: Whether the company can manage foreign-currency liabilities and repayment obligations.
- Listing costs: Whether legal, advisory, compliance and exchange-related expenses are commercially justified.
A wider fundraising framework does not remove the need for strong financial discipline. Businesses must demonstrate that the capital raised can support sustainable operations and future growth.
A Wider Step Towards Global Capital Market Integration
The November 2026 amendments are part of a broader effort to make India’s capital market framework more flexible and internationally connected.
For Indian companies, the changes provide additional ways to approach global investors. For GIFT City, they strengthen its potential role as a platform for cross-border financial activity.
The rules also show that international fundraising is not limited to large, established businesses with conventional balance sheets. Conditional access for companies with negative net worth could create opportunities for businesses seeking capital after financial restructuring.
The real test will be whether companies use these provisions to raise productive capital, rather than treating overseas listing as an objective in itself. Strong disclosures, investor protection and regulatory confidence will remain essential. If the framework attracts credible issuers and long-term investors, it could help India deepen its connection with international capital markets and strengthen GIFT City’s position as a financial centre.
Nadia Al-Hassan
Nadia Al-Hassan focuses on the economics of AI, semiconductors, cloud infrastructure, cybersecurity and digital sovereignty.